There’s a line item hiding in your benefits package that most payroll teams never think about until December, and some never think about at all. If your company provides group-term life insurance, and the coverage for any employee exceeds $50,000 — a threshold that has been in place for decades; confirm current treatment with your advisor — the IRS says part of that benefit is taxable income, even though the employee never sees a dime of it in cash. It has to show up on their W-2. And the only clean way to get it there is through payroll, before your final 2026 run.
This is the classic “nobody owns it” problem. The benefits team set up the life insurance policy and considers their job done. The payroll team processes what’s in the system and assumes benefits flagged anything taxable. The broker assumes the client is handling reporting. Meanwhile, the imputed income for group-term life, GTL for short, sits unrecorded all year, waiting to become a December scramble or a January failure.
Here’s the part that raises the stakes: unlike a lot of year-end tasks, this one has a hard mechanical cutoff. Imputed income needs to flow through an actual payroll run to be taxed and reported correctly. Once your last payroll with a 2026 check date has processed, your easy options are gone. The 2026 W-2 deadline, February 1, 2027 since January 31 falls on a Sunday, arrives whether your GTL was recorded or not.
When your company pays for group-term life coverage above $50,000, the IRS treats the value of the excess coverage as compensation. Not the death benefit, and not the premium your company actually pays. Instead, the taxable value is calculated using the IRS’s standard age-based rate table, commonly called Table I, which assigns a monthly cost per $1,000 of excess coverage based on the employee’s age. Older employees generate more imputed income for the same coverage because the table rates climb with age.
The employee never receives this money. It’s “imputed,” added to their taxable wages on paper so the right taxes apply. It’s subject to Social Security and Medicare taxes, and it appears on the W-2 both in total wages and as a separately coded item. The actual Table I rates and the mechanics of the calculation are something to confirm with your advisor or in current IRS guidance; the point for right now is that the amount exists, it’s taxable, and your system needs to know about it.
Any employee whose employer-provided group-term life coverage exceeds $50,000 is in scope. In practice, the people most commonly missed fall into a few groups:
That’s a starting list, not a complete one. Retirees and terminated employees with continued coverage have their own rules worth a conversation with your advisor, and the full population review is laid out in the Ignite HCM Year-End Checklist (ignitehcm.com/yearend-guide).
The salary-multiple case deserves special mention. A plan offering coverage at two times salary means every employee earning over $25,000 is over the threshold. In most companies, that’s nearly everyone, and the imputed income calculation has to reflect each person’s age and coverage amount individually.
ADP Workforce Now can handle GTL imputed income smoothly, including calculating and applying it on a recurring basis throughout the year, which is the setup that makes Decembers boring in the best way. But whether your plan runs it per-payroll or in a single year-end batch, the amounts must process on a payroll with a 2026 check date to land in 2026 wages.
The reason is withholding. Imputed income is taxable, and the Social Security and Medicare taxes on it need to be collected from the employee’s real wages. When GTL flows through a regular payroll, taxes come out of a normal paycheck and nobody feels much. When it’s crammed into the last check of the year, a year’s worth of imputed income hits one paycheck, and the withholding bite is noticeable, right at the holidays. When it misses payroll entirely, you’re left trying to collect taxes on wages that were never run, which is an unpleasant administrative corner to be in.
Skip the GTL entry and several things go wrong at once. The W-2 understates taxable wages, which makes it incorrect the moment it prints. Social Security and Medicare taxes were never withheld, so the company has an uncollected tax problem and may end up covering amounts it then has to sort out with the employee. If the miss is caught after W-2s are issued, you’re into corrected W-2s, and if it’s caught after employees have filed their personal returns, some of them get to amend. If it’s never caught, the exposure simply sits there, compounding year over year, waiting for an audit or an employee’s sharp-eyed accountant to find it.
None of this is exotic. GTL is one of the most commonly missed taxable fringe benefits at year-end, precisely because it involves no cash changing hands. Out of sight, off the W-2.
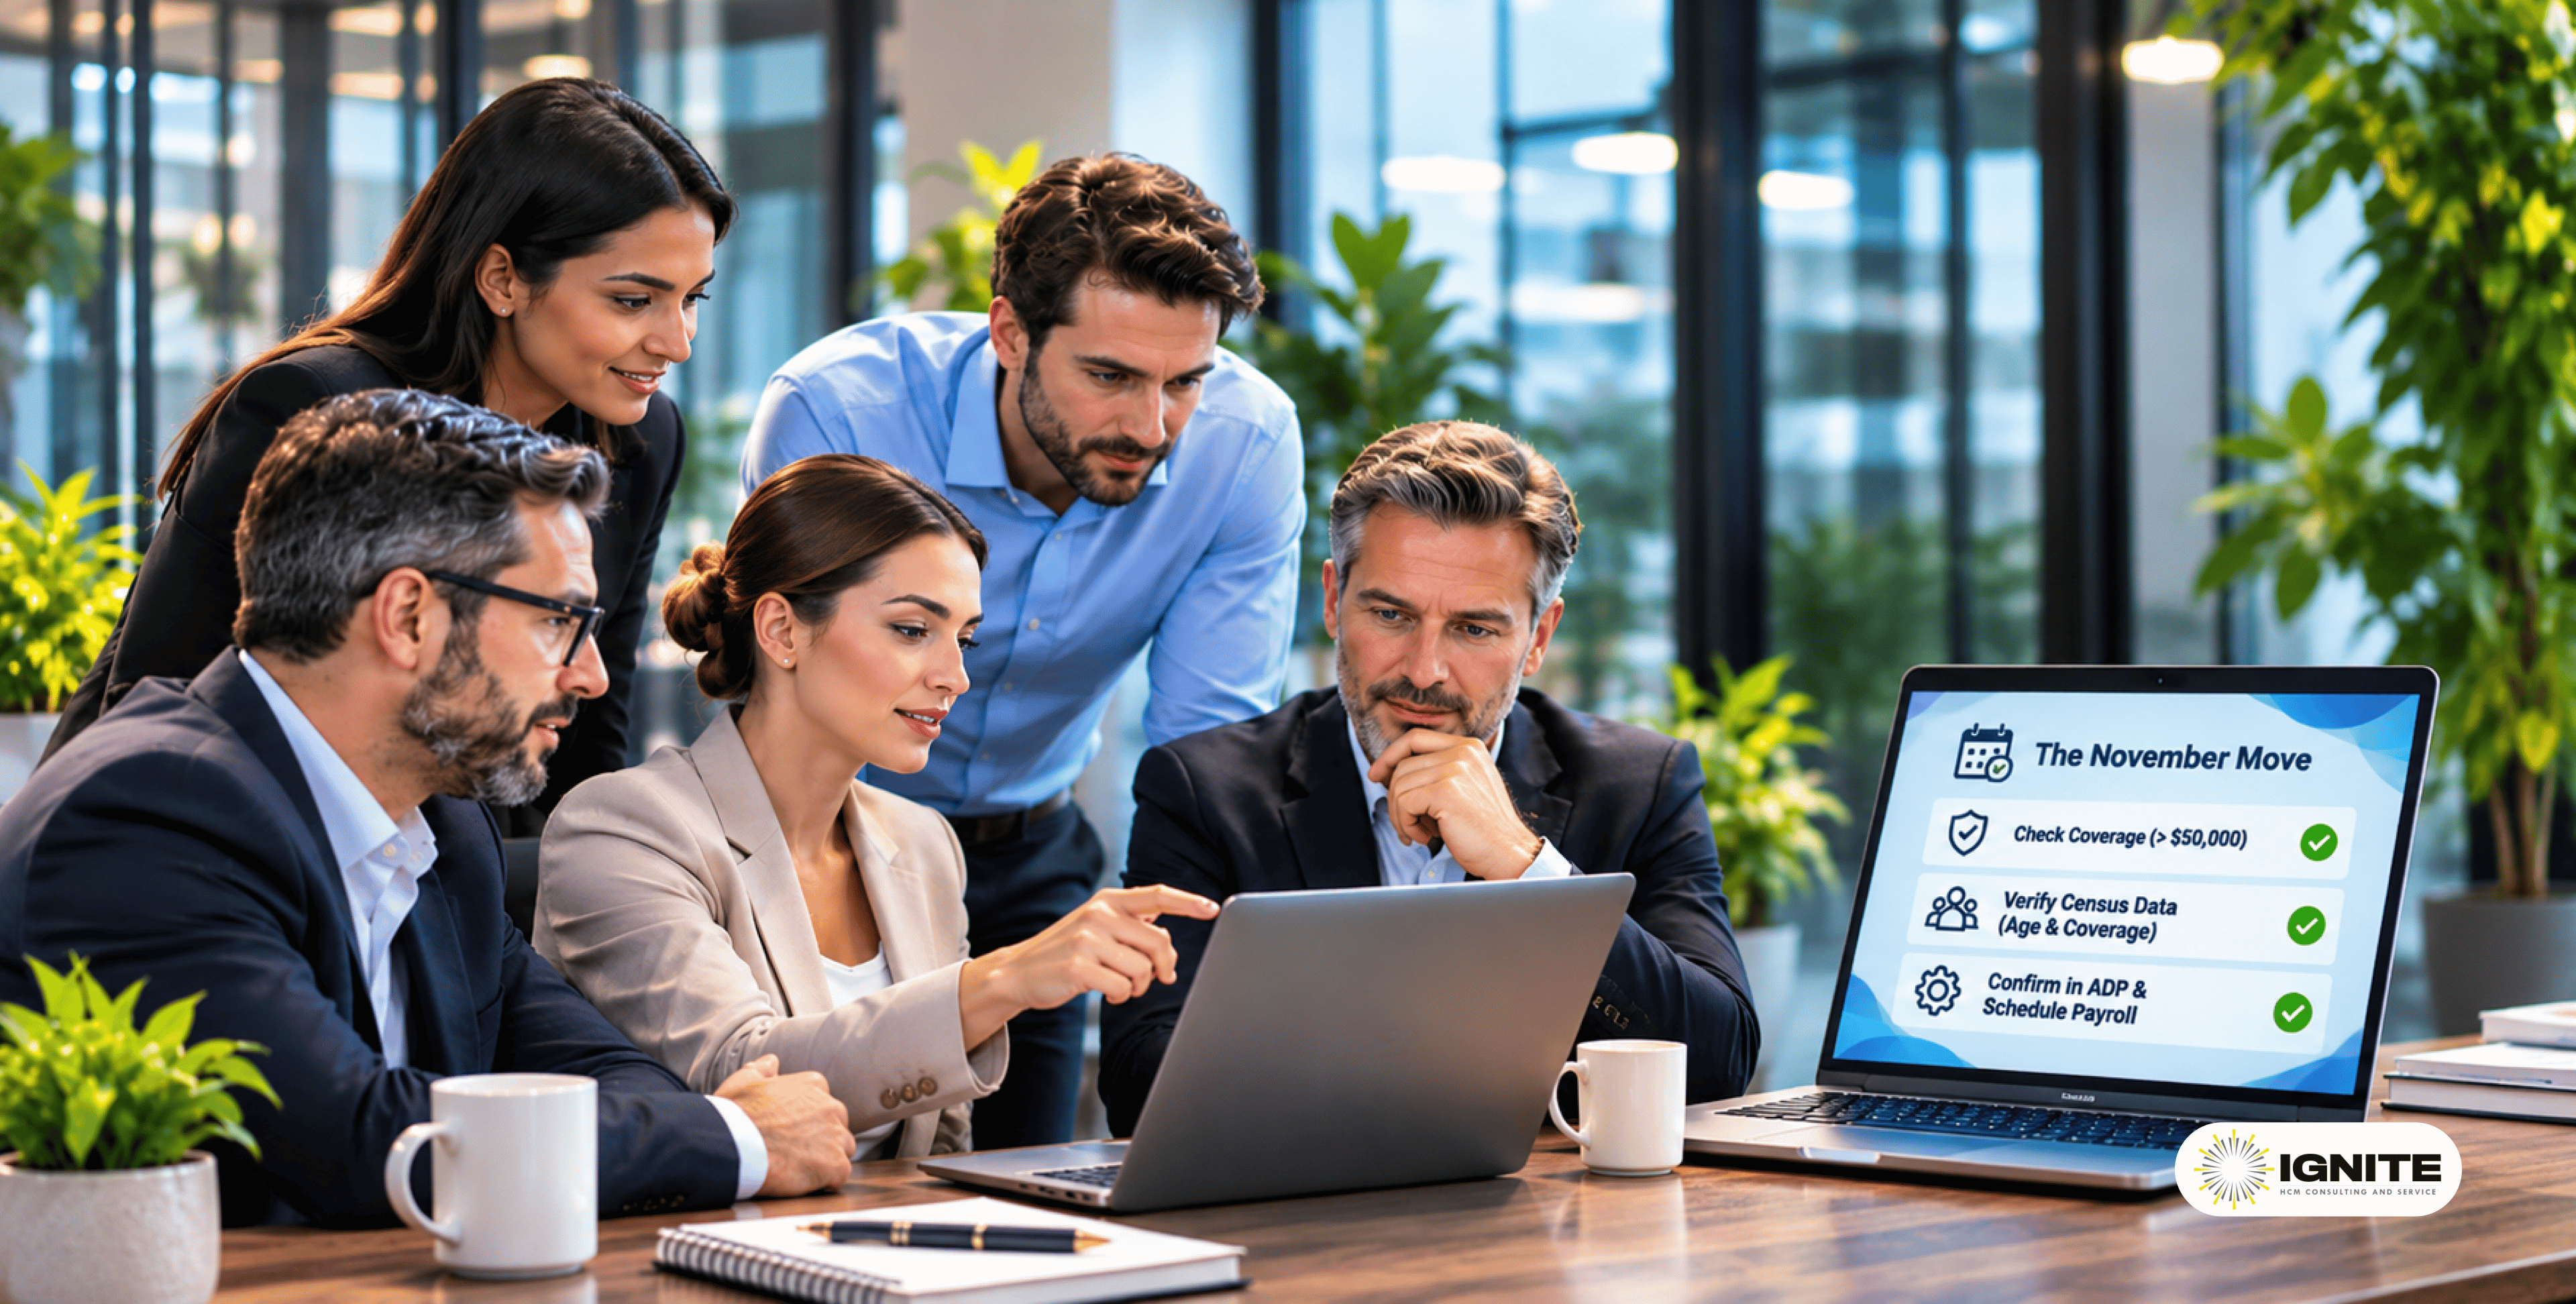
The work right now is verification, not calculation. Confirm whether your plan provides coverage over $50,000 for anyone. Confirm whether ADP Workforce Now is already recording imputed income each pay period, because if it is, your December just got easier, and if it isn’t, you’ve found the project. Confirm your census data, especially ages and coverage amounts, since the whole calculation keys off them. Then get whatever is missing scheduled onto a payroll run with time to spare before your last 2026 check date. Each of those steps has details worth doing carefully, and that’s exactly the kind of walk-through we do with clients every November.
A typical case: a company of about 150 employees offers life insurance at two times salary, a generous benefit nobody ever connected to payroll. No imputed income gets recorded for years. The gap surfaces during an unrelated benefits review in January, after W-2s have already gone out.
The cleanup covers the current year plus the prior-year exposure: corrected W-2s for dozens of employees, amended employment tax filings, uncollected Social Security and Medicare taxes the company ultimately absorbs for prior years, and professional fees to calculate several years of age-based imputed income person by person. The bill lands well into five figures, and it dwarfs what the fix would have cost in December — an annual payroll entry that takes an afternoon to set up. The sentiment we hear from CFOs at that point is always some version of the same realization: they were paying for a benefit and buying a liability.
If no employee’s employer-provided group-term life coverage exceeds $50,000, the imputed income requirement generally doesn’t apply. The caution: verify that’s actually true, especially with salary-multiple formulas, mid-year raises, and executive tiers. “I think we’re under the limit” is how most of these misses start.
Before your final payroll with a 2026 check date processes. Realistically, earlier, because you want time to verify census data and review the first calculation. If you’re starting from zero in mid-December, you’re already tight.
Understated W-2s, uncollected payroll taxes, potential corrected forms for multiple years, and audit exposure that grows with each year the miss continues. Prior-year cleanup is a conversation for your tax advisor, but the first step is always the same: stop the miss for the current year.
Ignite HCM is former ADP service professionals working with ADP clients exclusively. We know where GTL setup lives in ADP Workforce Now, how to get a year of imputed income in cleanly before the final run, and how to make it automatic so next December is quiet. No ticket queue. A dedicated consultant who has done this exact cleanup more times than we can count. We’ve got you.
Year-end is won in November, not January. Grab the free Ignite HCM Year-End Checklist (ignitehcm.com/yearend-guide) — or REQUEST A CONSULTATION (ignitehcm.com/solutions/compliance) and we’ll run it with you.
ADP and the ADP logo are registered trademarks of ADP, Inc. This article is general guidance only, not tax or legal advice. Confirm current IRS Table I rates and the treatment of your specific plan with your licensed tax advisor.