Every December, accountants across the country send the same email to their S-corporation clients: “Don’t forget, the health insurance premiums for the owners need to be on the W-2.” And every January, a healthy percentage of those emails turn out to have arrived too late, gone to the wrong person, or been read by someone who assumed payroll already handled it. The result is the most predictable year-end fire drill in small-business payroll, and it lands squarely on the owners themselves.
Here’s the rule at a general level. If you own more than 2% of an S-corporation and the company pays for your health insurance, those premiums have to be included in your W-2 wages. The IRS treats them as compensation to you, not as an ordinary company benefit. There’s a real upside buried in this: handled correctly, the reporting typically preserves the owner’s ability to deduct those premiums on their personal return. Handled incorrectly or not at all, that deduction is at risk, and the W-2 is simply wrong.
The catch is timing. Those premiums have to flow through payroll, and payroll runs on check dates. Once your final payroll with a 2026 check date has processed, getting 2026 premiums onto a 2026 W-2 stops being a routine entry and starts being a correction project. That’s why this is a December task with a November planning step, not a January task. January is when you find out whether you did it.
S-corporation owners live under special rules because they stand on both sides of the paycheck. For shareholders owning more than 2%, the tax code generally treats company-paid health premiums as additional wages. They’re reported on the W-2, typically subject to income tax withholding treatment that differs from regular pay, and they appear both in taxable wages and as an informational item so the owner’s personal tax preparer can see exactly what happened.
The reporting isn’t busywork. It’s the bridge to the owner’s personal deduction for self-employed health insurance. No W-2 reporting, and that bridge may be out. The dollars involved are rarely small, either. Family health coverage premiums commonly run well into five figures a year, which means the amount missing from a botched W-2 is well into five figures too.
One more wrinkle worth confirming with your advisor: the more-than-2% rule can extend beyond the named shareholder. Ownership attribution rules can pull certain family members who work for the company into the same treatment. If a spouse, parent, or child of an owner is on the payroll and on the health plan, that’s a question to ask now, not in February.
Before anything goes into ADP, someone has to build the list of affected people and amounts. At minimum, that means identifying:
That’s the core of it, and each item has edge cases (mid-year ownership changes, partial-year coverage, reimbursement arrangements) that deserve care. The fuller worksheet, alongside every other owner-level year-end item, is in the Ignite HCM Year-End Checklist (ignitehcm.com/yearend-guide).
The mechanics force the timing. The premium amounts need to process on a payroll run with a 2026 check date to land in 2026 wages. Most companies handle it on one of the final payrolls of the year, once full-year premium totals are known. That means the information gathering — premium totals from the insurance invoices, ownership percentages, affected family members — has to be done before that run, which puts the real work in late November and early December.
Miss the window and your options get ugly fast. The W-2 goes out wrong and needs a corrected form. Or it goes out late while you scramble, risking the February 1, 2027 deadline for 2026 W-2s (January 31 is a Sunday). Or, worst case, nobody notices until the owner’s personal return is being prepared in March, at which point the company is amending payroll filings while the owner’s return sits on hold, and possibly their deduction with it.
This task fails in the gap between two professionals. The company’s accountant knows the ownership percentages and the deduction strategy but doesn’t run payroll. The payroll contact runs ADP but may not know who owns what or which premiums count. Each assumes the other has it.
The fix is a short three-way conversation in November or early December: accountant, payroll, and whoever manages the health plan. Confirm the shareholder list, confirm the premium totals, confirm who is entering what into ADP and on which payroll run. Fifteen minutes on a call in November replaces hours of forensic email archaeology in February. If your accountant hasn’t raised it yet, raise it with them. They will be delighted, and a little surprised.
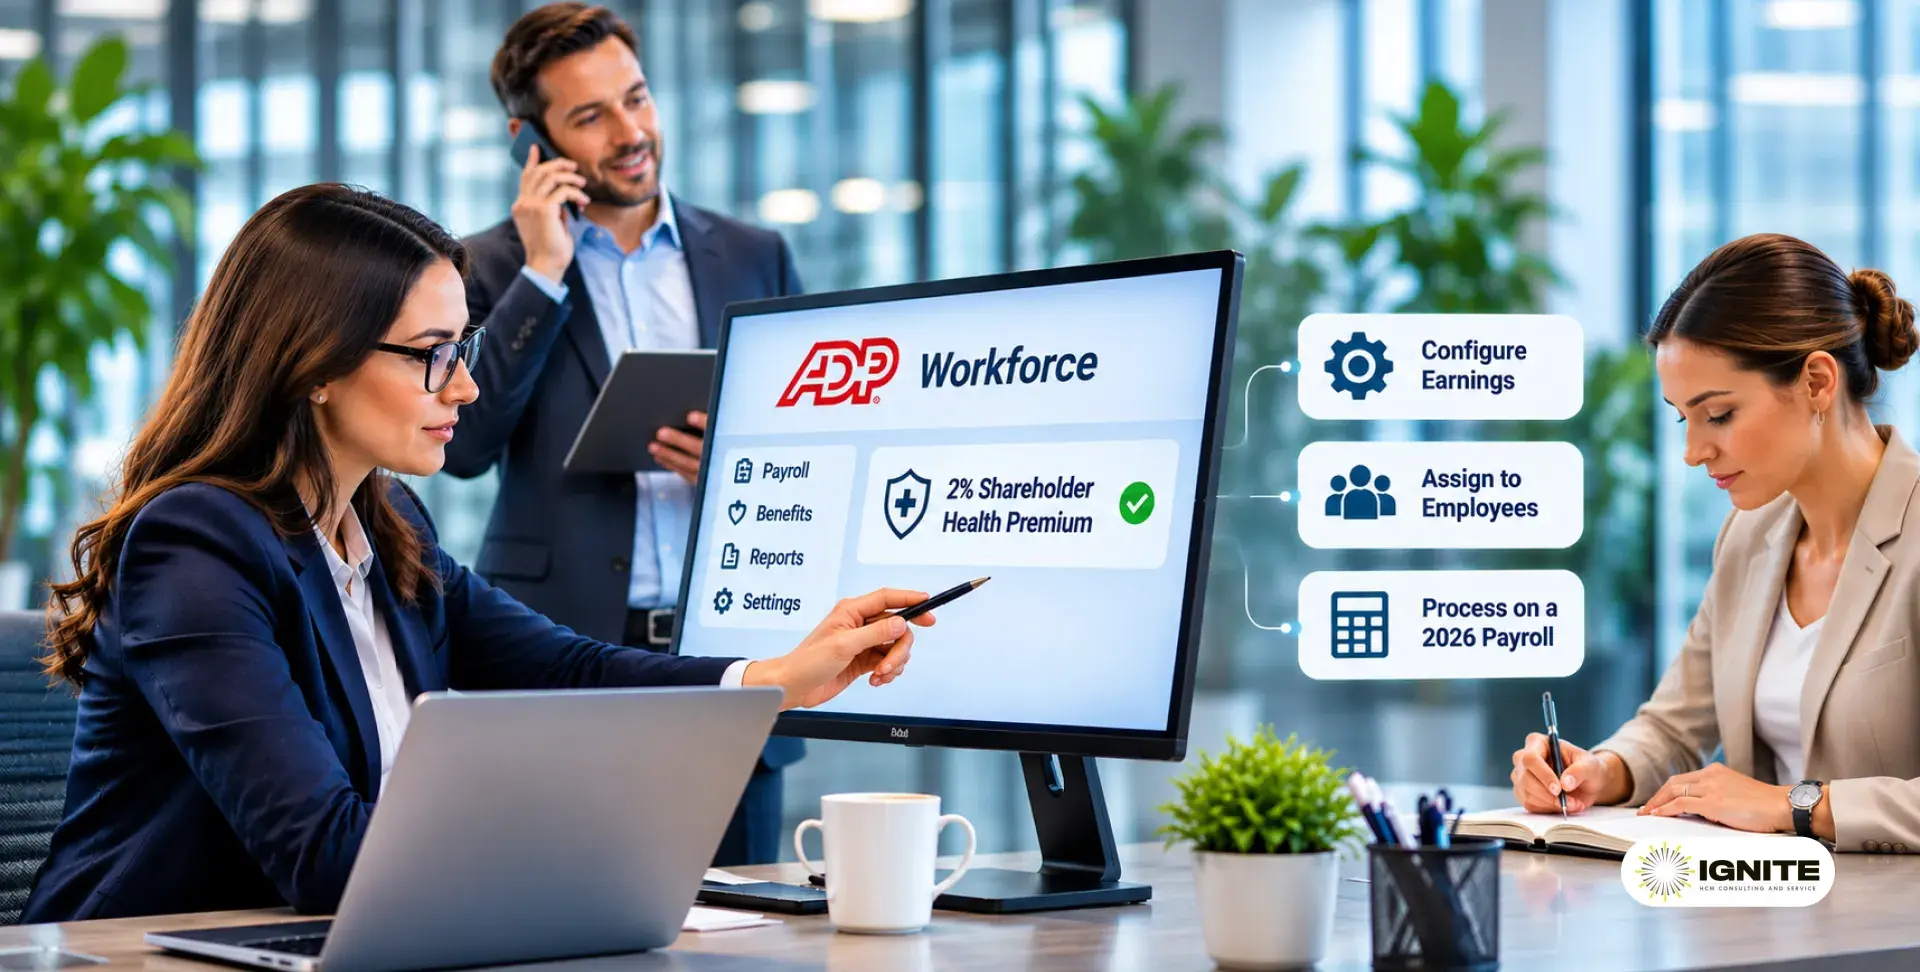
ADP Workforce Now handles 2% shareholder health premiums through specific earnings setup designed for exactly this situation, so the amounts tax and report the way the rules require. The setup work involves getting the right earnings configuration in place, the right people attached to it, and the right amounts processed on a 2026-dated run. The specifics depend on your plan, your state, and your payroll calendar, and the margin for error is thin: getting it almost right produces W-2s that look fine and aren’t. This is precisely the kind of task where an hour with someone who has done it a few hundred times pays for itself.
A typical case: a professional services S-corporation with three owner-shareholders assumes their outside accountant is handling the premium reporting, while the accountant assumes the payroll administrator is. A full year of company-paid family health premiums across the three owners — well into five figures — never touches payroll. The W-2s go out in January looking clean.
The gap surfaces in March, when one owner’s personal tax preparer asks why the W-2 shows no health insurance amounts. By then: corrected W-2s for all three owners, amended employment tax filings, three personal tax returns on hold during the busiest season of the year, and a tense debate about whether the deduction can be preserved at all. The professional fees for the cleanup dwarf what the December fix would have cost, and one owner’s refund sits delayed for months. Done on time, this is a single adjustment entry and a calendar reminder.
1. “The company doesn’t pay my premiums directly. Does this still apply?”
Maybe. Reimbursement arrangements and premiums paid personally but reimbursed by the company can fall under the same reporting rules. The ownership question matters too, including family attribution. If you own more than 2% and health insurance money moves through the company in any direction, ask your advisor now.
2. “When does this absolutely have to be done?”
The premium amounts need to process on a payroll run with a 2026 check date, so your true deadline is your final December run. The planning conversation with your accountant should happen weeks before that, while there’s still time to gather premium totals and fix surprises.
3. “What’s at stake if we skip it?”
An incorrect W-2 that will likely need correction, amended payroll filings, a delayed personal tax return, and risk to the owner’s health insurance deduction, which on family coverage can be a five-figure deduction. The people harmed most are the owners themselves.
Ignite HCM serves ADP clients exclusively, and our consultants came up through ADP’s own service teams. We’ve set up 2% shareholder health reporting in ADP Workforce Now for companies of every size, and we’re comfortable getting on the phone with your accountant so nothing falls in the gap between you. No ticket queue, no re-explaining your situation to a stranger. One dedicated consultant, start to finish. We’ve got you.
Year-end is won in November, not January. Grab the free Ignite HCM Year-End Checklist (ignitehcm.com/yearend-guide) — or REQUEST A CONSULTATION (ignitehcm.com/solutions/compliance) and we’ll run it with you.
ADP and the ADP logo are registered trademarks of ADP, Inc. This article is general guidance only, not tax or legal advice. The 2% shareholder rules, attribution questions, and deduction treatment depend on your facts. Confirm them with your licensed tax advisor.