You found the perfect candidate. The only catch: she lives in a state where your company has never had an employee. The offer is signed, the start date is three weeks out, and someone just asked the question that stops the room: "Are we even set up to pay her there?"
If your stomach dropped a little reading that, you are in good company. Hiring across state lines is a common growth moment, and it is also one of the easiest places to create a compliance mess that follows you for quarters. A new state usually means new tax accounts, new registration timelines, new unemployment rates, and sometimes local taxes you have never heard of. None of it is hard, exactly. It is just unfamiliar, sequenced, and unforgiving of shortcuts.
The fix is a repeatable checklist, worked in order, started the day the offer goes out. Here is the process we walk clients through every week, including where ADP does the heavy lifting and where the work is yours alone. We've got you.
The single most important thing to know: you generally need to register with the new state before you run your first payroll there, and registration is not instant. Some states issue account numbers online the same day. Others take two to six weeks, and a few route paper forms through review queues that move at their own pace. If the start date is three weeks away and the state needs four to issue numbers, you have a timing problem no software can solve.
So the moment a candidate in a new state gets serious, start the clock. Identify what the state requires, begin the applications, and only then move on to system setup. ADP can calculate, withhold, file, and deposit for the new state, but it cannot invent your account numbers. Those come from the state, to you, on the state's schedule.
One helpful framing: hiring one remote employee in a state usually creates "nexus" there, meaning the state now considers you an employer within its borders, with payroll tax obligations and sometimes other registrations to match. The payroll piece is what we cover here; loop in your advisors on the rest.
Most states with a personal income tax require employers to register for a withholding account before remitting employee income tax. The application typically asks for your federal EIN, legal name and address, entity type, the date of your first payroll in the state, and an estimate of the wages you will pay there. That first-payroll date matters, because it sets when your filing obligations begin.
When the state issues your withholding account number, it usually assigns a deposit frequency too: how often the withheld tax must be sent in, based on your expected liability. Both the number and the frequency need to end up in ADP, exactly as issued. A mistyped account number is one of the most common causes of misapplied payments and state notices, so copy from the state document, not from memory.
A handful of states have no personal income tax on wages and need no withholding account. Do not relax yet, because the next account applies almost everywhere.
State unemployment insurance is a separate registration with a separate agency in most states, and it applies even in states without income tax. When you register, the state assigns you an employer account number and, critically, your SUI rate: the percentage of each employee's wages, up to that state's wage base, that you pay in unemployment tax. New employers typically receive a standard new-employer rate that later adjusts based on your claims history.
That rate must be entered in ADP exactly as the state assigned it. If the system calculates at a placeholder rate while the state expects your actual rate, every payroll builds a small over- or under-payment, and quarter end becomes a reconciliation project. When the state later mails a rate change notice, usually annually, that update needs to be made too. A surprising share of the tax notices we untangle for clients trace back to a SUI rate that was never updated.
While you are with the unemployment agency, check for companion items: some states bundle in training surcharges or assessments, and a few run separate programs like paid family leave with their own registrations and rates.
State-level accounts are only part of the picture in some parts of the country. Several states have city, county, or school district income taxes, and a few metro areas have their own payroll or transit taxes. If your new hire lives or works in one of these places, you may need an additional registration, and the employee's home address, not just the work address, can determine what applies.
This is where precise address data earns its keep. ADP determines local tax jurisdictions from the addresses in the system, so a sloppy address can mean a missed local tax or a wrong one. Enter the full, validated address, confirm the jurisdictions the system proposes, and if the employee lives in a known local-tax state, verify against the local rules rather than assuming the defaults caught everything.
Local taxes are small individually and expensive collectively. Missing one for a year means back taxes, penalties, amended filings, and an awkward conversation with the employee. Ten minutes of verification up front is the cheap version.
With account numbers in hand, the system work is straightforward. The new state gets added as a tax jurisdiction for your company, with the withholding account number, the SUI account number, the SUI rate, and the deposit frequencies the state assigned. If ADP is handling your tax filing and deposits, this is also what connects the new state into that service, so filings and payments start flowing automatically.
Then set up the employee: work location, home address, the state withholding certificate for her state (many states have their own form and do not simply reuse the federal W-4), and any local codes. Before the first live payroll, run a preview and read the tax lines. You should see the new state's withholding and the employer-side unemployment calculating. If a tax you expected is missing, or one you did not expect appears, stop and resolve it before you commit. It is far easier to fix a preview than a filed quarter.
Here is the pitfall that generates more state notices than any other. When registration is still pending, it is possible to set a jurisdiction up in an "applied for" status so payroll can run while you wait for numbers. It is a useful bridge. It is a terrible permanent state.
While a jurisdiction sits in applied-for status, taxes are being withheld from employees, but filings and deposits may not be reaching the state correctly, because there is no account number to file under. Every payroll that runs this way deepens the hole. When the number finally arrives, someone has to enter it, and the missed or held filings have to catch up. If nobody owns that follow-through, the applied-for status quietly persists for months, and the first sign of trouble is a penalty notice.
The rule we give every client: applied-for is a bridge measured in weeks, with a named owner and a calendar reminder. The day the state letter arrives, the number goes into ADP the same week, and you confirm the catch-up filings happened. If a jurisdiction has been in applied-for status for more than a quarter, treat it as an active problem.
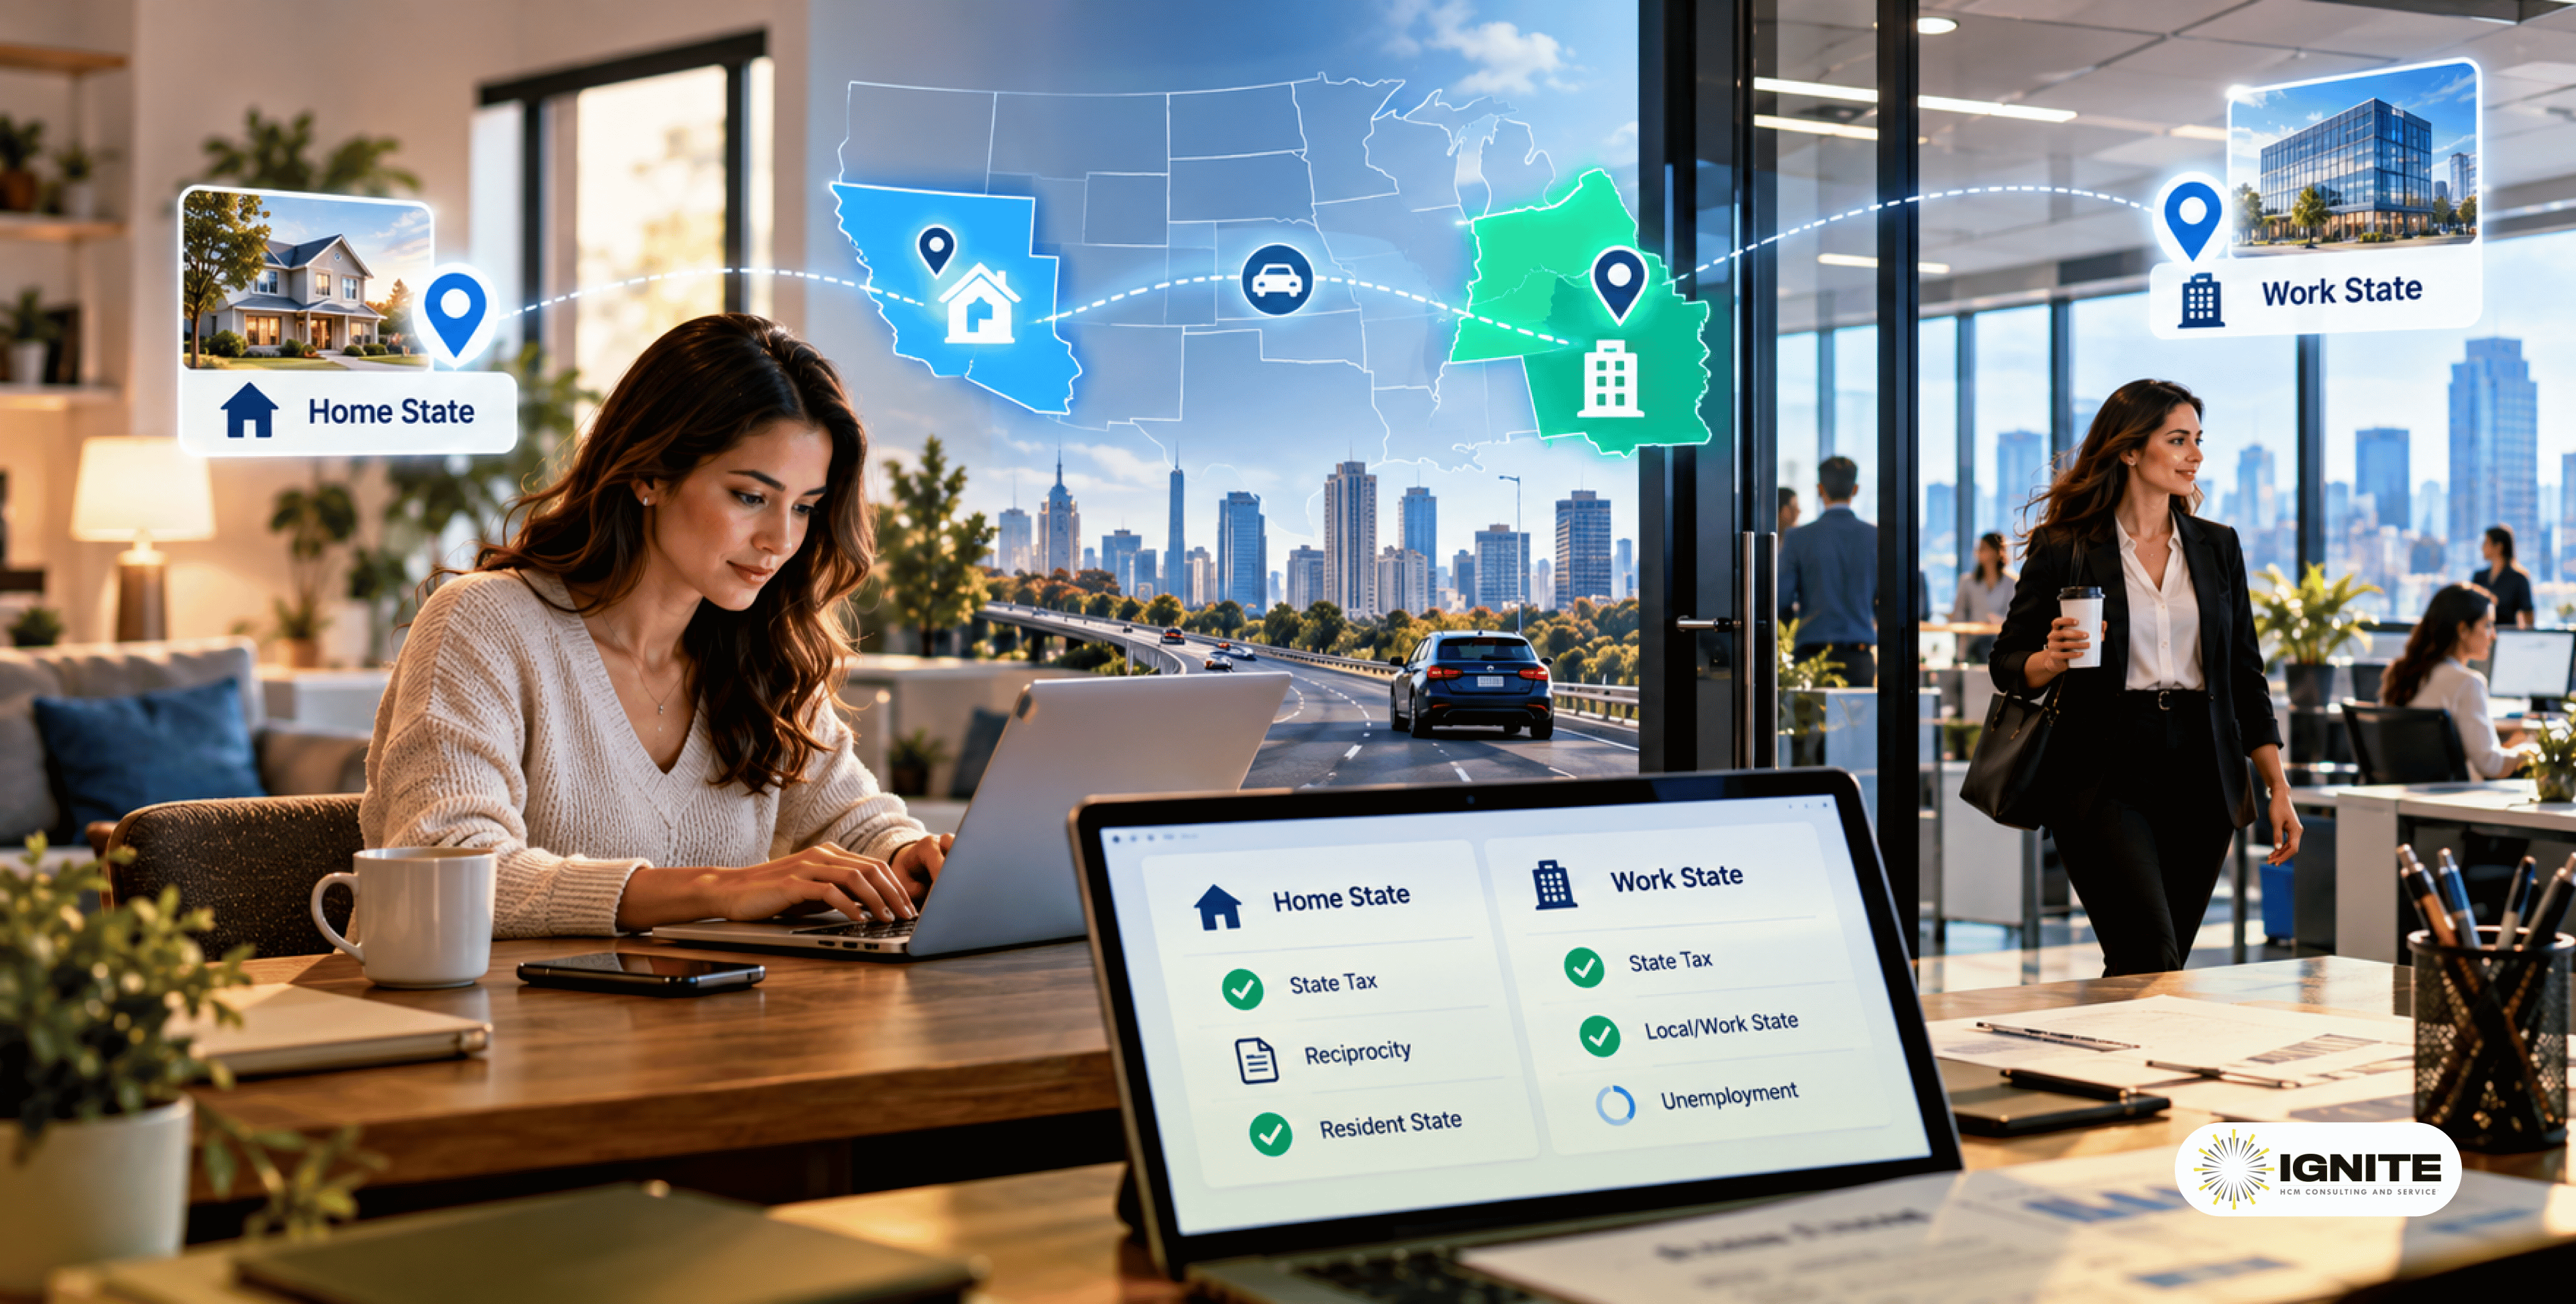
Sometimes the new hire does not fit neatly in one state. She lives in one and commutes to an office in another, or splits the week between home and headquarters. Now you are in multi-state territory, and the general rule is that wages are taxed where the work is physically performed, with the resident state often taxing income too and granting a credit.
Some neighboring states simplify this with reciprocity agreements: the employee files a certificate, and you withhold only for the resident state. Others do not, and a few apply special rules to remote workers whose employer is based in-state. Unemployment is its own analysis, since SUI is generally owed to one state per employee under a location-based test, not split between them.
The practical takeaway: capture where the employee actually lives and actually works, set both correctly in ADP, and have the reciprocity or credit question answered before the first payroll rather than after. When arrangements are unusual, confirm the treatment with your tax advisor and set the system to match the answer, not the other way around.
A client with about 150 employees, all in one state, hired a senior engineer in a neighboring state with a start date four weeks out. Here is how the timeline ran. Week one: we identified the registrations needed, and the client applied online for withholding and unemployment accounts, listing the first payroll date. The withholding number arrived in three days; the unemployment account took nearly three weeks and came with a new-employer SUI rate of roughly 3 percent on the first $10,000 of wages, round numbers for illustration.
Week two: the employee's home county turned out to have a local income tax, which the client had not anticipated. We verified the jurisdiction from her validated address and added the local registration. Week three: the unemployment number arrived, and all accounts, rates, and frequencies went into ADP the same day, with the state added to the tax filing service. Week four: payroll preview showed state withholding, the local tax, and employer SUI all calculating, and the first payroll ran clean on her start date.
Total client effort was a few hours spread over a month. The same hire attempted the week before the start date would have meant an applied-for bridge, a local tax likely missed entirely, and cleanup stretching into the next quarter. The difference was not skill. It was starting the clock on offer day.
You can physically run it, and that is the problem: the taxes get withheld with nowhere proper to go. Registering late risks penalties, held filings, and notices. If timing is truly tight, use applied-for status as a short, owned bridge, never as the plan.
Registration is the employer's obligation, though support services exist to help with the paperwork. What ADP does superbly is everything after: calculating, withholding, depositing, and filing, once your account numbers and rates are in the system. Think of it as: the state credentials you, ADP operates for you.
Generally, yes. One employee working in a state creates employer obligations there for payroll taxes, and often for unemployment insurance from the first dollar of wages. Headcount does not matter; presence does.
The first new state is a scramble. The fifth should be routine, and here is what routine looks like. A one-page checklist per hire: registrations identified on offer day, applications submitted within the week, account numbers and rates entered in ADP the day they arrive, employee addresses validated, a payroll preview reviewed line by line before the first live run, and a standing rule that applied-for status carries an owner and an expiration date. Keep a simple register of every state you operate in, its account numbers, its SUI rate, and its renewal cadence, and review it each quarter.
Do that, and new-state hiring stops being a fire drill and becomes what it should be: good news about a growing company.
If you would rather hand the whole sequence to someone who has run it hundreds of times, that is us. Ignite HCM is staffed by former ADP service professionals, and we work with ADP exclusively. No tickets, no hold queues, just a dedicated consultant who knows exactly which state does what, and in what order. Hair on fire? Call us.
Hiring across state lines and not sure you're covered? REQUEST A CONSULTATION.
ADP and the ADP logo are registered trademarks of ADP, Inc. This article is general guidance, not tax or legal advice; state rules vary and change, so confirm specifics with your licensed advisor.